DRC Cobalt Quotas Tighten Global Supply as LFP Batteries Surpass 55% of EV Battery Market
The Democratic Republic of Congo’s efforts to restrict cobalt exports have tightened global supply, but the rapid growth of cobalt-free lithium-iron-phosphate (LFP) batteries is creating a new challenge for the country’s strategy.
Cobalt prices initially surged after the DRC introduced restrictions, but prices have since corrected as battery manufacturers increasingly shift towards chemistries that use little or no cobalt.
The DRC introduced an annual cobalt export quota of 96,600 tonnes for 2026 and 2027, comprising an 87,000-tonne base quota and a 9,600-tonne strategic quota.
The ceiling represents roughly half of the country’s previous export volumes, according to S&P Global.
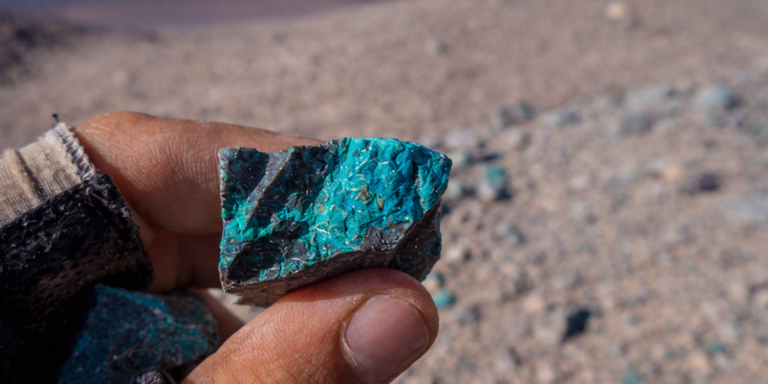
The restrictions initially had a significant impact on prices. Cobalt, which traded at about US$21,000 a tonne at the beginning of 2025, climbed above US$56,000 a tonne in January 2026.
However, Trading Economics reported the price at US$40,120 a tonne on September 17, representing a 28.73% decline over one month.
The decline has highlighted the growing influence of battery technology on cobalt demand. According to the International Energy Agency, LFP batteries accounted for more than 55% of batteries deployed in electric vehicles globally in 2025, up from almost 50% a year earlier.
Unlike nickel-manganese-cobalt (NMC) batteries, LFP batteries contain no cobalt. Their adoption has been particularly rapid in China and emerging markets, reducing the extent to which rising electric-vehicle sales translate into higher cobalt demand.
In China, the shift has been even more pronounced. LFP batteries accounted for about 82% of battery production in the second quarter of 2026, while the share reached 84.6% in July, according to data cited by S&P Global.
The research firm projected that Chinese EV-related cobalt demand could fall 9.6% from 2026 levels to 35,564 tonnes by 2030, even as EV sales increase.
The DRC’s supply restrictions have also encouraged other responses from consumers and manufacturers, including greater use of recycled cobalt and efforts to diversify supply.
Indonesia is emerging as another source of cobalt supply, with S&P Global forecasting mine production of about 53,300 tonnes in 2026, with further growth expected in 2027.
Recycling is also becoming more important, while China remains dominant in battery-material processing and recovery capacity.
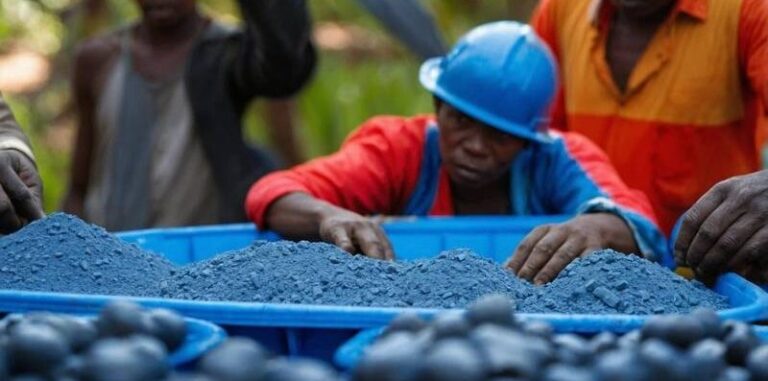
Despite these changes, the DRC remains by far the world’s largest source of mined cobalt, and the metal continues to be used in NMC batteries, electronics, superalloys and other industrial applications.
The country is also facing challenges on the production side. An electricity deficit of more than 1.2 GW has affected mining operations, while industry requirements could rise to about 5 GW by 2030. Higher-cost thermal power has been used to supplement insufficient grid supply.
Logistics are another cost pressure for mining companies operating in the Congolese Copperbelt, with road congestion, border crossings and long distances to ports adding to operating expenses.
Meanwhile, the DRC’s mineral regulator, ARECOMS, has continued tightening control over cobalt volumes.
In June, it decided to transfer unused first-half quotas into the strategic quota rather than allowing the volumes to accumulate under producers’ allocations.
The changing market means the effectiveness of the DRC’s cobalt strategy will depend not only on how much material is exported, but also on how battery manufacturers respond to higher cobalt prices.
For the DRC, the challenge is therefore increasingly about capturing greater value from each tonne of cobalt while maintaining demand for the metal.
The combination of export volumes, prices, tax revenues and the pace of substitution into cobalt-free battery technologies will be critical to determining the long-term impact of the country’s supply strategy.
About the Author